
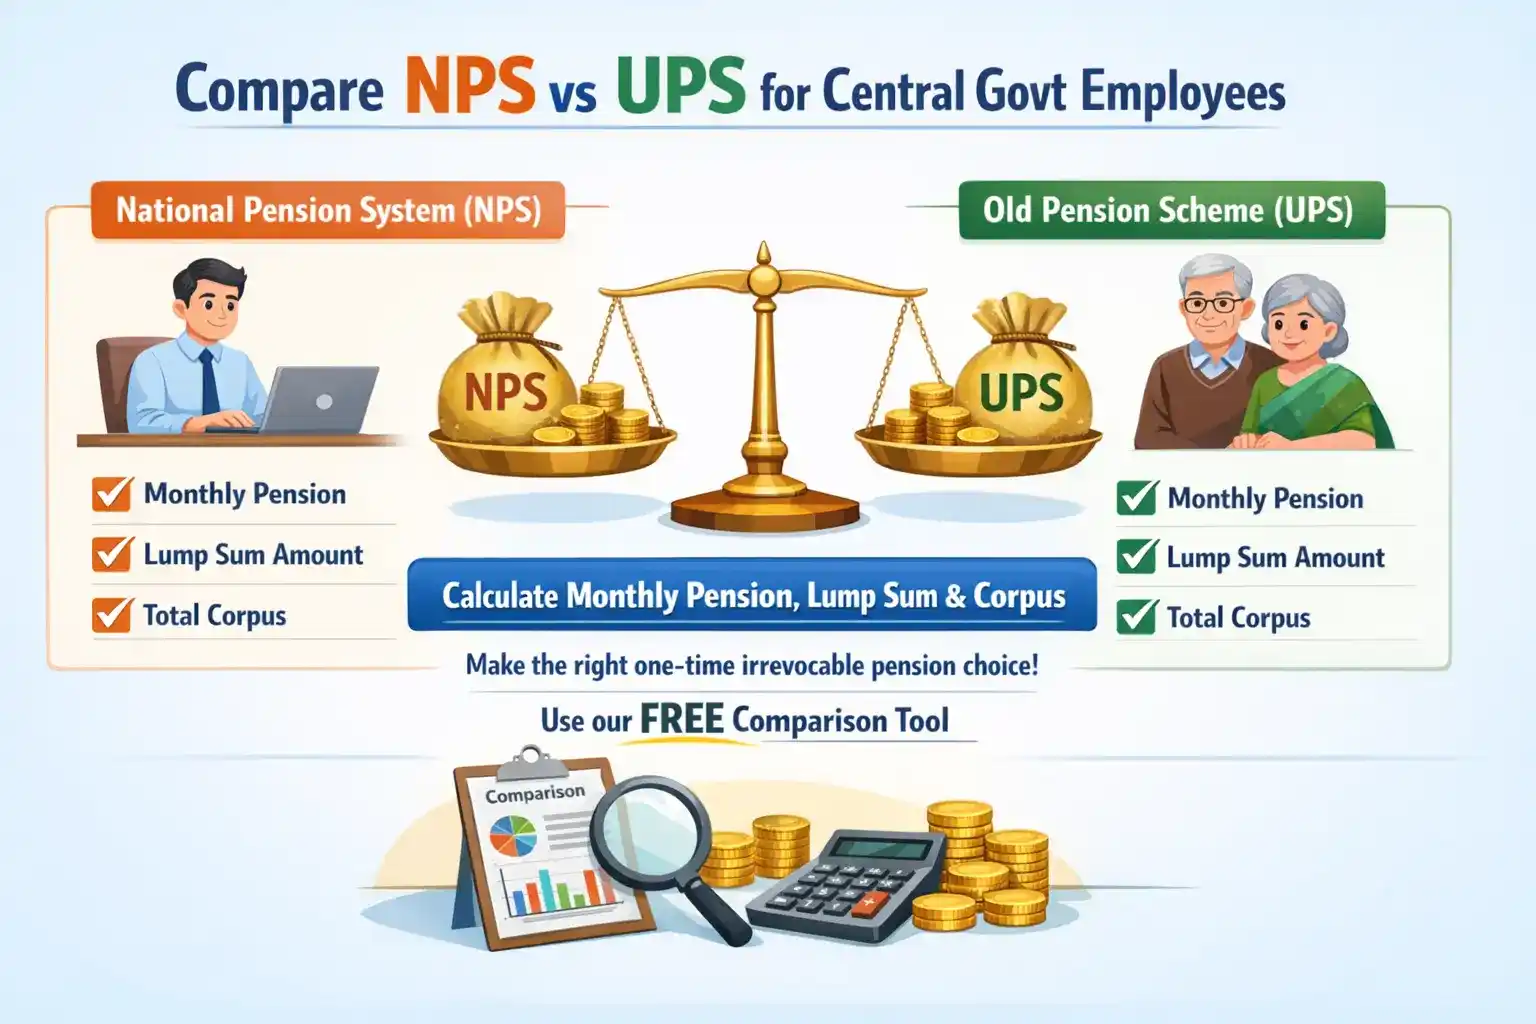
NPS vs UPS Comparison: The Government of India introduced the Unified Pension Scheme (UPS) in August 2025. It gives Central Government employees who joined after January 1, 2004 and are currently covered under NPS the option to switch to a defined-benefit pension system. This is a one-time and irrevocable choice, which means once you select UPS or stay with NPS, the decision cannot be changed later.
UPS guarantees 50% of the average basic pay of the last 12 months as monthly pension after 25 years of service, with a minimum guaranteed pension of ₹10,000 per month. NPS, on the other hand, is market-linked — your final pension depends on your investment returns over your service period.
Use NPS vs UPS calculator to compare: Enter your expected basic pay at retirement and years of service. The tool will calculate your estimated monthly pension, lump sum amount, and total corpus under both NPS and UPS, and give you a personalised recommendation based on your numbers.
NPS vs UPS Calculator
Pension Scheme Comparison for Central Govt Employees
Others Free Tools
| Resource | Link |
|---|---|
| Income Tax CalculatorFY 2025-26 | Click here to Calculate |
| Gratuity Calculator | Click here to Calculate |
| Pension Calculator for CG Employee | Click here to Calculate |
| LTC Calculator 2026 | Click here to Calculate |
| 8th CPC Salary Calculator | Click here to Calculate |
| DA Hike Calculator | Click here to Calculate |
| Age Calculator Online | Click here to Calculate |
| MACP Eligibility Checker | Click here to Calculate |
| DA Calculator 2026 | Click here to Calculate |
| NPS Corpus Estimator For Govt Employees | Click here to Calculate |
| KMA & ALK Arrear Calculator | Click here to Calculate |
Frequently Asked Questions — NPS vs UPS
Q: What is UPS and how is it different from NPS?
A: UPS (Unified Pension Scheme) is a defined-benefit pension scheme launched by the Government of India in August 2025. Under UPS, the pension amount is guaranteed — you receive 50% of your average basic pay from the last 12 months before retirement (for 25+ years of service). NPS (National Pension System) is a market-linked scheme — your pension depends on the returns from your NPS Tier-I account invested in equity, government bonds, and corporate bonds.
Q: What is the minimum pension guaranteed under UPS?
A: Under UPS, the minimum guaranteed pension is ₹10,000 per month for employees with at least 10 years of qualifying service. If your calculated 50% pension is less than ₹10,000, the government tops it up to ₹10,000. This minimum guarantee does not exist under NPS — your NPS pension depends entirely on market returns.
Q: What happens to family pension under UPS vs NPS?
A: Under UPS, if the employee dies after retirement, the family pension is 60% of the employee’s last drawn pension. Under NPS, the nominee receives the annuity corpus (40% of total corpus that was compulsorily used to buy annuity). The exact family pension amount under NPS depends on the annuity plan chosen at retirement.
Q: What is the government contribution under UPS vs NPS?
A: Under NPS: Government contributes 14% of Basic Pay + DA. Under UPS: Government contributes 18.5% of Basic Pay + DA. In both cases, the employee contributes 10% of Basic Pay + DA. The higher government contribution under UPS (4.5% more) is one of the key advantages of switching.
Q: Is the NPS vs UPS choice truly irrevocable?
A: Yes. As per the official government notification, the choice between NPS and UPS is a one-time, permanent decision. Once you opt for UPS, you cannot switch back to NPS, and vice versa. The option window was open initially for existing NPS subscribers — new employees who joined after August 2025 can also choose at the time of joining.
Q: What lump sum amount will I get at retirement under UPS?
A: Under UPS, you receive a lump sum equal to 1/10th of monthly pay (Basic + DA) for every completed 6 months of service at retirement. This is in addition to the monthly pension. For example, if you have 30 years of service (60 half-years) and your last monthly pay (Basic+DA) is ₹1,00,000, your lump sum = ₹1,00,000 ÷ 10 × 60 = ₹6,00,000.
Q: What if I have less than 25 years of service — how is UPS pension calculated?
A: If you have between 10 and 25 years of qualifying service, your UPS pension is proportionate. The formula is: Pension = (Average Basic Pay of last 12 months × 50% × Years of Service) ÷ 25. So with 20 years of service, your pension would be 40% of average basic pay. The minimum guarantee of ₹10,000 still applies if you have at least 10 years.
Q: Will Dearness Relief (DR) be added to UPS pension?
A: Yes. Under UPS, Dearness Relief (DR) at the same rate as DA for serving employees will be added to the pension amount. This means your pension will increase automatically every time the government announces a DA hike. This is a significant advantage of UPS over NPS, where no such inflation protection is built in.
🔗 Related Tools Section
Explore our other free tools for Central Government employees:
- DA Calculator 2026 — Calculate your monthly Dearness Allowance at 60% (Jan 2026)
- 8th CPC Salary Calculator — Calculate your 8th Pay Commission salary w.e.f 1st Jan, 2026
- MACP Eligibility Checker — Check your Modified Assured Career Progression status
- LTC Calculator 2026 — Calculate Leave Travel Concession reimbursement for the new block
11 thoughts on “NPS vs UPS Calculator 2026 — Which Pension Scheme is Better for You?”